Marry the House, Date the Rate: Will Mortgage Rates Come Back Down?
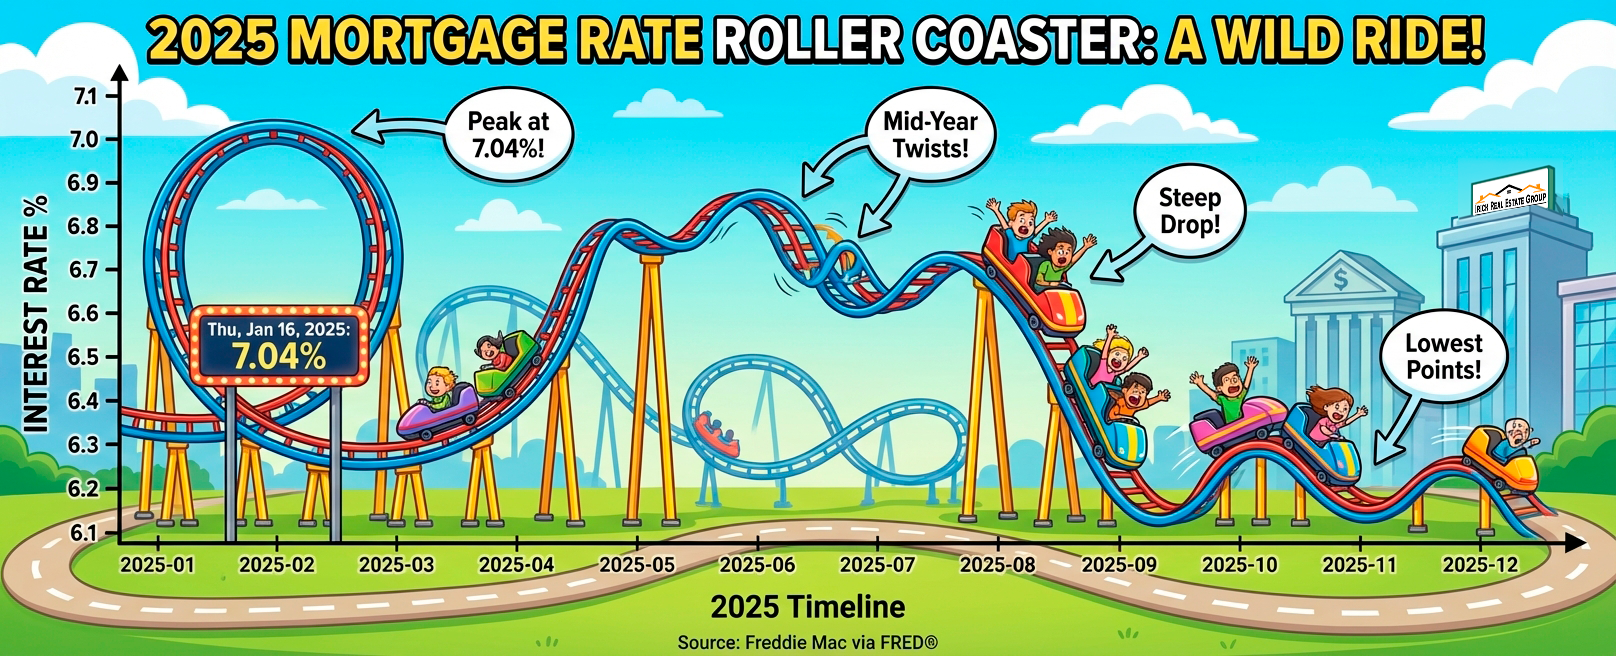
“Marry the house, date the rate.” It’s been four years — and the rate is still waiting on that second date.
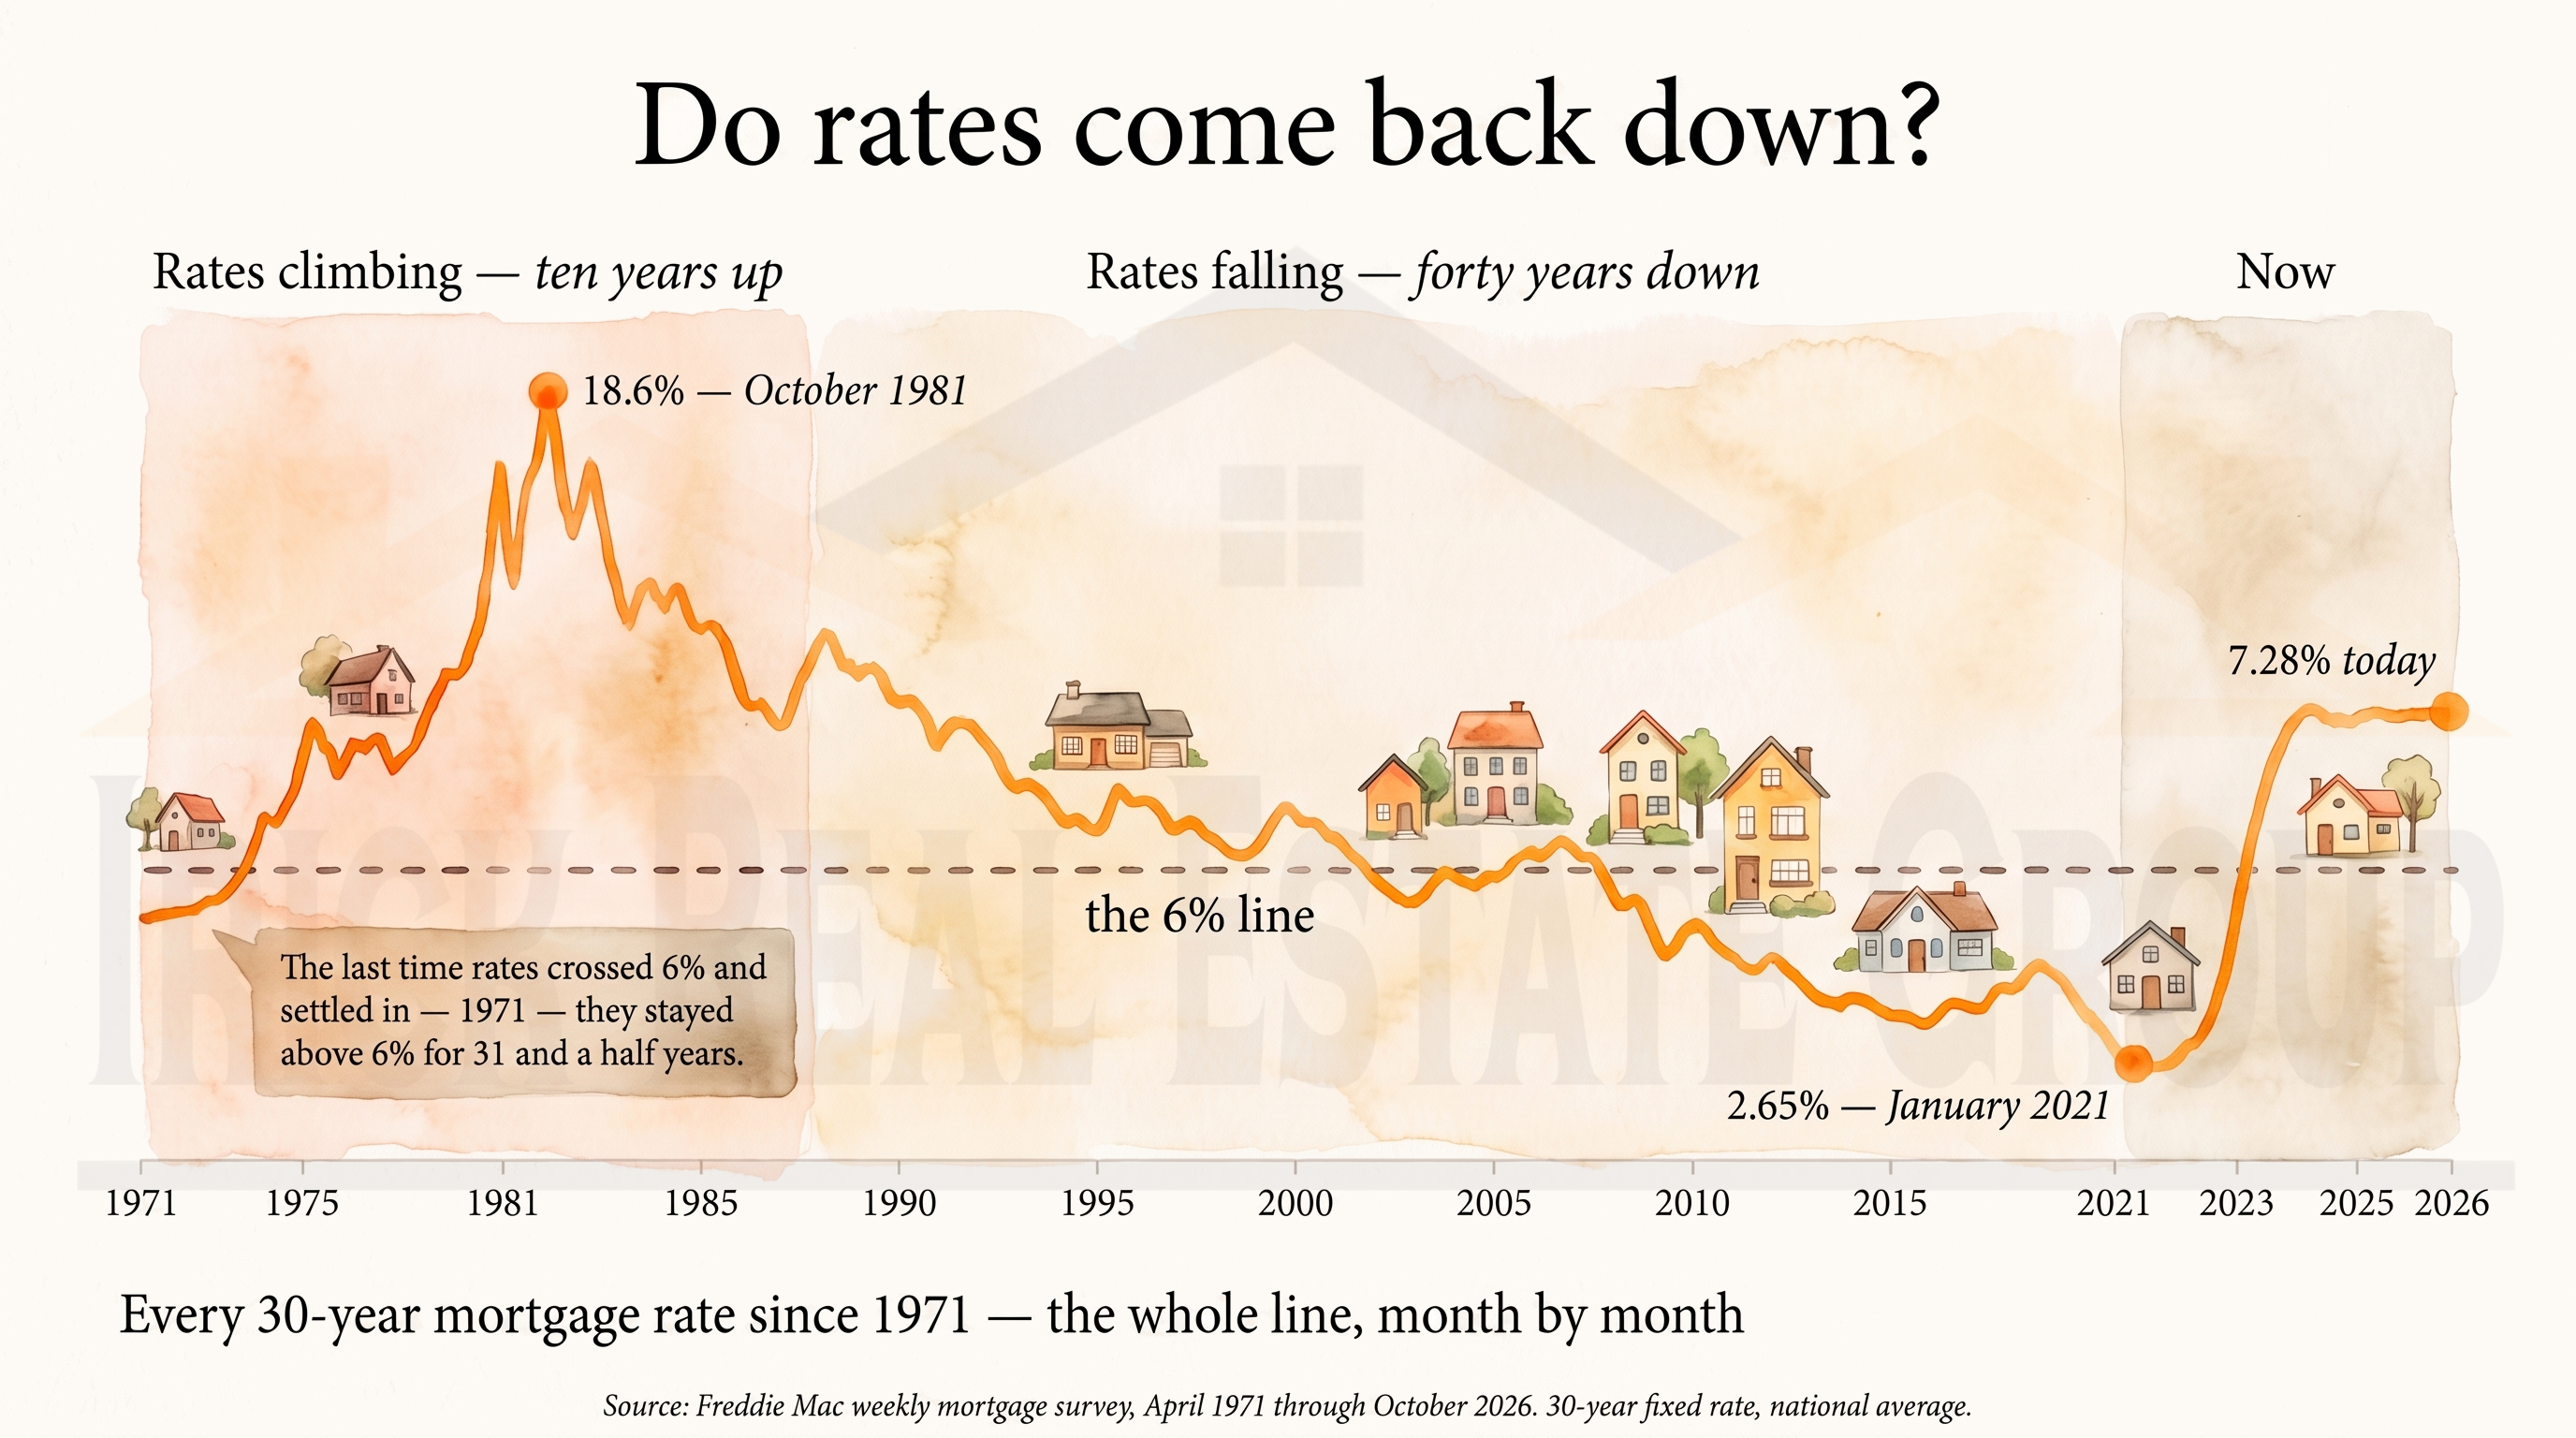
If you bought a home in the last few years, somebody probably said those words to you: take today’s rate, refinance when rates come back down. It’s the most repeated piece of real estate advice of this decade. So this week I checked it against history — every weekly mortgage rate Freddie Mac has published since April of 1971, all 2,896 of them — and asked one plain question: when rates go up, do they actually come back down?
The honest answer is that it depends entirely on which market you were born into, and there have only been three. From late 1981 to early 2021, rates fell for forty straight years — 18.6% all the way down to 2.65% — and in that world the advice was simply true: a rate a full point lower, the usual threshold where a refinance pays for itself, showed up within five years for three out of four buyers, and within ten years for nearly all of them. The typical wait was under two years. Every agent working today learned the business inside that world. But there was a world before it. From 1971 to 1981 rates climbed for a decade, and buyers who waited for them to come back waited a long time — for a family who bought in 1971 at 7.33%, a meaningfully lower rate didn’t arrive until 2002. Thirty-one years. Once rates crossed 6% in 1971, they stayed above 6% for thirty-one and a half years without a single week below.
Which brings us to the world we’re in now. Rates crossed 6% in September of 2022 and have spent the four years since above it, with one exception: two weeks this past February, when they touched 5.98%. A family who locked in around 7% in late 2022 and has been dating that rate ever since needed to see 5.94% for the refinance to make sense. The best week in four years missed it by four hundredths of a point — and it lasted fourteen days. This week that family is looking at 7.28% by Freddie Mac’s weekly average — the same measure as every number in this story — which is higher than the rate they were told to date, and rates have climbed more than six tenths since the middle of August.
One thing I want to say in fairness: the agents who repeated that line weren’t being dishonest. Forty years of falling rates taught an entire industry that patience always paid. But I’ll tell you why you’ve never heard it from me. In thirty-four years, I have never once told a client to count on a refinance — and it’s not because I saw this market coming. I didn’t, and neither did anybody else. Nobody controls mortgage rates, and nobody can tell you with certainty where they’re headed — not the Fed, not the economists on television, and certainly not me. The only advice I’ve ever been comfortable giving is advice that still works if the future doesn’t cooperate. As I understand this job, that’s the whole job.
So what do you do with this? If you’re buying, buy the payment, not the forecast — if the number works at today’s rate, a refinance someday is a gift, not a plan. And buying still beat waiting: the families who bought in 2022 have four years of ownership behind them, while the folks who held out for rates to come back have paid four years of rent watching prices move. If you’re selling, understand that every buyer walking through your door is carrying a 7% payment with no rescue coming — which is exactly why pricing to this fall’s market matters more than ever. The market doesn’t owe anyone a do-over, but it rewards the people who deal with it as it is. If you’re weighing a move this fall and want to run the numbers at real rates — today’s, not hoped-for — that’s exactly the conversation I’m here for. I’m here to help.
Chance Kirby - Irick Real Estate
940.300.6900
Want to know what this means for your home? Call or text Chance Kirby at (940) 300-6900 for a free price opinion based on recent sales near you.